
Abstract:
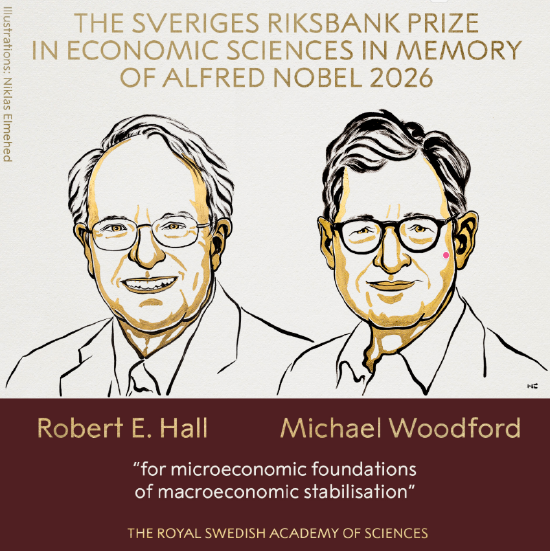
The Royal Swedish Academy of Sciences announced on October 12 that the 2026 Nobel Prize in Economics will be awarded to American economists Robert E. Hall and Michael Woodford in recognition of their theoretical foundation for New Keynesian macroeconomics. The research of the two economists has promoted changes in macroeconomic policy analysis methods, allowing economists to explain the relationship between interest rates, consumption, inflation and business cycles starting from the micro-decisions of households and businesses. Relevant theories are now widely used in the policy-making process of central banks and fiscal authorities around the world.
An oil crisis puts traditional economic theory in trouble
Why do central banks often cut interest rates when economic growth slows? Why does raising interest rates become the main policy tool when inflation is out of control?
These seemingly familiar economic policies involve a question that has been studied by the economics community for nearly a century: How should the government and the central bank regulate the economy to avoid severe recession and continued inflation?
This problem can be traced back to economist John Maynard Keynes. He argued that household and business demand for goods and services does not always automatically align with the economy's productive capacity. When demand is insufficient, companies reduce production, the unemployment rate rises, and the economy falls into recession; when demand is too strong, production capacity cannot meet consumption and investment needs, and inflation may accelerate. Therefore, the government can stimulate demand by increasing spending, cutting taxes, etc., and the central bank can affect economic activity by adjusting interest rates.
Traditional Keynesian models mainly rely on historical statistical relationships between macroeconomic variables, such as the relationship between unemployment and inflation, and the relationship between household income and consumption.
However, the oil crises of the 1970s upended some of the assumptions on which these models were based.
As energy prices rise sharply, many economies simultaneously
Qualcomm
inflation, high unemployment and stagnant economic growth. According to the simple relationship in traditional models, rising unemployment should usually be accompanied by falling inflation, but the reality is that both worsen at the same time. The original economic stabilization policy has therefore encountered challenges. Mistimed stimulus measures not only fail to solve the economy's problems but could further push up inflation.Economists have gradually realized that simply observing the statistical relationship between inflation, unemployment and consumption is no longer enough to explain complex economic changes. To understand macroeconomics, one must re-examine how each household and business makes economic decisions.
Hall's reversal research idea: household consumption cannot be predicted in advance
In macroeconomics research, household consumption is always one of the most important variables.
Traditional theory usually holds that
as household income increases, consumption will increase accordingly
. But economists have found that household consumption behavior in reality is much more complex. For example, even if a household's income does not increase this year, it may increase consumption in advance if it expects that its income will increase significantly in the next few years. In turn, even if current income is high, households may choose to save more if they fear future unemployment.This means that consumption is determined not only by current income, but also by people's judgments about the future.
The problem is that future revenue expectations are difficult to observe and measure directly. For a long time, economists have been looking for indicators that can reflect household expectations in the hope of predicting changes in consumption, but it has always been difficult to achieve satisfactory results.
In 1978, Hall proposed a different research idea. He believes that if households indeed arrange consumption based on expectations of future income, then current consumption levels actually reflect the information held by households. Only when new information emerges that changes households' judgments about the future will consumption plans need to be adjusted. And truly new information cannot be predicted before it appears.
From this, Hall came to a seemingly counter-intuitive conclusion:
If the theory is true, changes in household consumption itself should not be systematically predictable in advance.
This changes the direction of the research question. Economists no longer need to search for indicators that can accurately predict changes in consumption, but can examine whether existing variables can systematically predict future changes in consumption. Hall's research provided important empirical support for this theory and established a benchmark for subsequent consumption research.
In 1982, he and economist Frederic Mishkin further conducted research using household microdata and found that the consumption behavior of about 80% of households in the sample was in line with relevant theories, while the remaining households were closer to relying on current income to maintain daily expenses.
These findings help economists understand why the same fiscal or monetary policy affects different households differently.
Woodford builds a new model: Why is central bank expectations management so important?
If Hall helped economists understand how households decide to consume, then Woodford went further
integrating household expectations, corporate pricing and central bank interest rate policy into a unified macroeconomic framework
.In 2003, Woodford published a work that systematically elaborated on the New Keynesian theory. The macro model based on microeconomics became an important model for subsequent research.
At its core, this model views the macroeconomy as the result of the interaction of a large number of households and businesses. Households decide consumption and savings based on income expectations and interest rates, companies decide the selling prices of goods based on production costs, market demand and future price expectations, and the central bank affects these behaviors through interest rate policies.
One of the important concepts is the natural interest rate, which is the level of interest rate that neither stimulates nor inhibits economic activity.
When the policy interest rate is lower than the natural interest rate, borrowing and current consumption may be stimulated; when the policy interest rate is higher than the natural interest rate, consumption and investment demand may be suppressed. But Woodford's research further points out that the way central banks influence the economy is not limited to the current level of interest rates.
How people believe interest rates will change in the future can also change today's economic decisions
.For example, if a company expects that production costs and other commodity prices will rise in the future, it may adjust pricing in advance even if current costs have not increased significantly. Savings and consumption decisions may also change in advance if households anticipate lower interest rates in the future. Therefore, whether the central bank can clearly and credibly explain its policy objectives and future actions to the market plays an important role in stabilizing economic expectations.
This also provides a theoretical basis for modern central banks to attach great importance to policy statements, interest rate guidance and inflation expectations.
From 1970s stagflation to modern central banks: What happened to economic stabilization policies?
Another important contribution of the Woodford model is that it
helps economists distinguish the different impacts of demand changes and supply shocks on the economy.
For example, when oil prices suddenly rise, companies' production costs increase, and the economy may be able to provide fewer goods and services. Even if consumers don't increase spending, economic demand may appear too high relative to reduced production capacity, pushing up inflation. In this case, simply stimulating consumption may further expand the imbalance between supply and demand, while raising interest rates and moderately suppressing demand may help control inflation.
Woodford uses concepts such as the output gap to compare actual economic output with natural output levels, providing an analytical tool for judging whether economic demand is too strong. This framework enables policymakers to more systematically analyze the impacts of rising energy prices, supply chain disruptions and other external shocks.
The Royal Swedish Academy of Sciences pointed out that the New Keynesian model has been widely used by central banks and financial departments around the world, and has played an important role in responding to epidemics and energy crises in recent years. Of course, these models do not eliminate recessions and inflation and continue to evolve as the economic environment changes. Central banks in different countries need to adjust relevant models based on their own economic structures.
The far-reaching change brought about by Hall and Woodford's research is to establish a set of analytical methods for macroeconomic policy starting from micro behavior: by understanding how households consume, how companies set prices, and how people form expectations for the future, we can determine how interest rates and fiscal policies will affect the entire economy.
Today, when central banks discuss the natural interest rate, the output gap, inflation expectations, and the future path of interest rates, there is a theoretical foundation behind them that the two laureates helped establish.
Comments