
Abstract:
During the National Day holiday, let’s talk about a relaxing topic. Recently, the topic #5 Million Yu’e Bao’s Yield in One Day has become a trending topic on Weibo, triggering a heated discussion across the Internet about the threshold for financing and settling down in the era of low interest rates. In my opinion, the reason why this matter has become a hot search is not that 5 million is too small, but that many people suddenly discovered that in the era of low interest rates, the threshold for relying on risk-free interest has been significantly raised.
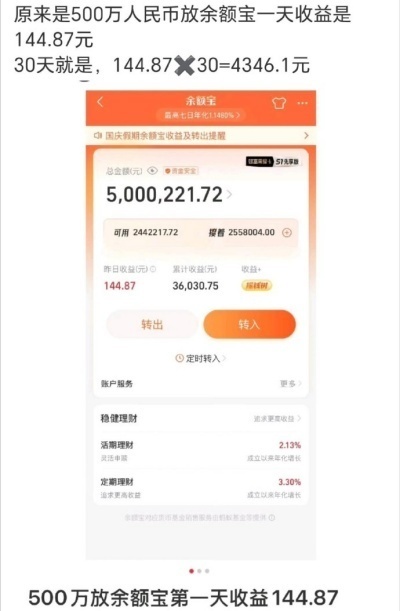
First do the math: According to the latest data from Tianhong Fund, Yu’e Bao’s seven-day annualized return rate is about 0.83%, and the income per 10,000 shares is about 0.2273 yuan. This means that if you put 5 million yuan in Yu'e Bao for one day, the income will be roughly 110-145 yuan, which mainly depends on the fluctuation of the income of 10,000 yuan that day. If you keep Yu'e Bao for one year, the income will be equivalent to 5 million × 0.83% = 41,500 yuan, which is about 3,458 yuan per month on average.
Therefore, putting 5 million into Yu'e Bao can indeed bring some passive income, but it is far from the level of being able to rest assured and not go to work. Don't imagine that you can rely on the interest of Yu'e Bao to settle down. Maybe you are curious, why is Yu’e Bao’s income so low?
The reason is very simple. Yu'e Bao is connected to monetary funds, which mainly invest in low-risk assets such as bank deposits, interbank certificates of deposit, short-term bonds, and reverse repurchases. The returns on these assets follow market interest rates. Now that the central bank remains loose and short-term interest rates are low, the safe returns that monetary funds can obtain are naturally not high.
More importantly, this is not the problem of Yu’e Bao alone. Since the beginning of this year, a large number of money funds in the market have fallen below 1% on a seven-day annual basis, and the entire industry has entered a stage of survival with low profits. Compared with ten years ago, Yu'e Bao's income gap is indeed very large, which makes people miss the past.
Around 2014, Yu’e Bao’s seven-day annualized rate was close to 6.7%. The same 5 million yuan was put into Yu'e Bao. At that time, the daily income could be close to 900 yuan, but now it is only more than 100 yuan, which is a very obvious shrinkage. However, one misunderstanding needs to be corrected: Yu’e Bao has never been a high-yield financial management tool, but more like a cash management tool. Its advantages are flexibility, low volatility, and ready availability. It is suitable for short-term reserve funds rather than long-term main assets.
For ordinary people, if they want to correctly understand and make good use of Yu'e Bao, they should do the following four points:
1. Don’t regard Yu’e Bao as a “flattening artifact”
It is suitable for holding emergency funds for 3-6 months, such as rent, living expenses, short-term disbursements, etc.
2. All large amounts of funds are put into monetary funds, and the opportunity cost is very high
If the funds are not used for a long time and all remain in the monetary fund at around 0.8%, it may not be able to beat inflation and it will be difficult to cover the real expenditure of households.
3. Consider asset tiered allocation
Daily money: money funds, cash management financial management; money not used for half a year to a year: short-term debt funds, interbank certificates of deposit index funds, savings bonds, etc.; spare money for more than one year: based on risk tolerance, consider bond funds, index funds, etc. However, it should be pointed out that any way to increase returns will bring about reduced liquidity or fluctuations in net worth.
4. Be wary of the trap of capital preservation and high interest rates
In the low interest rate environment, if someone promises high returns, zero risk, and can be withdrawn at any time, be careful to avoid being fooled.
In a nutshell, putting 5 million yuan into Yu'e Bao only earns more than 100 yuan a day. This is a normal market result, which determines that it can only provide limited cash flow. Being out of the hot search circle is more a collision between expectations and reality. In fact, the value of Yu'e Bao is to flexibly store small change, rather than as a value-added tool for large assets.
The first step in financial management is to understand that liquidity, security, and profitability cannot be maximized at the same time. In other words, what really needs to be solved is not where to put the money, but how to match the principal size, cash flow, expenditure level and risk tolerance. What do you think?
Author: Gong Jinhui
Comments