
Abstract:
In January this year, there was news that Asus would withdraw from the mobile phone market and lay off manpower in the mobile phone department. ASUS later responded that it had no plans to launch new smartphones this year, but the operations of its mobile phone business unit remained unchanged. But recently, the latest news from the supply chain shows that ASUS mobile phone inventory has been basically sold out in the fourth quarter. The inventory is cleared and there is no "relay" of new machines, which seems to announce the death of the brand.
The "last straw" that crushed Asus's mobile phone was the skyrocketing price of memory chips. When rising upstream costs push up mobile phone prices generally, more and more consumers are no longer willing to pay for niche brands, but are more inclined to invest their purchasing budget in leading mainstream models. At the same time, costs have risen, profits have shrunk, and niche mobile phone brands that have been unable to make much money have been forced to the edge of life and death.
Waiting for death and withdrawing from the market may be the outcome they have to accept after struggling for many years.
"Death List"
Around 2019, domestic niche mobile phones experienced a brutal "bloodbath":
After the thunderstorm of Gionee, it collapsed within a year. When it went bankrupt, its total debt was as high as nearly 21.1 billion yuan; Meitu published a farewell letter on Weibo, announcing that the brand of its Meitu mobile phones was fully authorized to Xiaomi Group; Smartisan Technology changed its legal person after being taken over by ByteDance, and all core members quit. "Idealist" Luo Yonghao left the mobile phone industry; 360 mobile phone business was rumored to be suspended, and the official reply was only to suspend it, but there have been no new phones since then.
At that time, the competition was extremely fierce, and the top position had initially taken shape. Seeing that there was no hope of "taking the table", other mobile phone brands chose to give up.
This year, another round of purges is coming, but this may be the last one.
In February, two days after the news of the suspension of its mobile phone business spread, Meizu finally responded, stating that it would suspend the research and development of new domestic mobile phone products and conduct strategic transformation. Before the business suspension was reported, Meizu had actually canceled the launch plan of 22 Air. In addition, Meizu 23 will not be released to the market. This already means that the former generation of "machine king" has entered the countdown to death and will disappear from the public eye.
As a company that has been established for 23 years, Meizu’s development has been full of ups and downs. It started brilliantly, but then due to strategic mistakes, the brand tone became blurred and sales declined. Then the founder returned and the generals fell out. The new machine was unable to turn the tide and could only survive on emotions until it was taken over by Geely.
Three years ago, Geely acquired Meizu and established Xingji Meizu Group. This was once regarded as a new starting point for Meizu. The then chairman and CEO Shen Ziyu set a goal: to return to the top five in the domestic mid-to-high-end market in three years. However, three years later, Meizu’s role is still awkward. Not only has it failed to realize its original ambitions, but it has been completely abandoned.
ASUS mobile phones have not had a good time these past two years. In the "cost-effectiveness" battlefield, the ZenFone series is difficult to shake the "machine sea tactics" and extreme cost control of mainland brands; in the "innovation" battlefield, it is unable to invest R&D resources that can rival the giants in cutting-edge fields such as imaging and folding screens. Therefore, the pace of product iteration has slowed down and the market volume has become weaker.
In fact, since last year, within the company, there have been few new moves in the mobile phone line. Now that the inventory has been cleared, the withdrawal of ASUS mobile phones is almost inevitable.
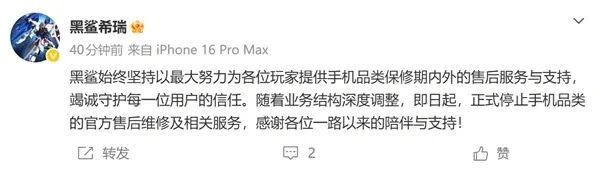
Also officially coming to an end this year is the former “king” of gaming phones, Black Shark. In June, Black Shark issued the "Announcement on Black Shark Community Server Upgrade and Service Migration", announcing that access to the Black Shark Community was temporarily suspended due to server upgrades; in July, Nanchang Black Shark Technology Co., Ltd.'s technical support engineer "Black Shark Xirui" announced that due to in-depth adjustments to the business structure, official after-sales maintenance and related services for mobile phone categories will be stopped.
The last time Black Shark released a mobile phone was in 2022. The Black Shark 6, which was originally planned to be launched in 2023, was still aborted after being warmed up. In the past few years, Black Shark has not launched any new mobile phones, and users have paid less and less attention to it, so that its end has hardly caused much fluctuation in the market.
In the field of gaming mobile phones, now only the Red Devils are left. Looking at the entire smartphone market, apart from those with backgrounds from major manufacturers, there are basically very few niche brands left.
Fatal blow
The smaller the size of the smartphone market, the more concentrated the market will be at the top.
According to IDC data, in the ranking of Chinese smartphone manufacturers' shipments in 2025, Huawei ranked first with shipments of 46.7 million units, followed by Apple and vivo with shipments of 46.2 million units and 46.1 million units respectively, with Xiaomi and OPPO occupying the remaining seats. The data also shows that the market share of these five manufacturers accounts for 79.4% of China's overall smartphone market share in 2025, and market concentration is increasing.
The same is true in other markets. For example, in North America, Apple has always been the undisputed king, and its market share has shown an upward trend in recent years. According to data, in the first quarter of 2022, Apple Intelligence mobile phones shipped 19.9 million units, with a market share of 51%; by the fourth quarter of 2025, Apple directly captured 69% of the market share, setting a record high.
Consumers are concentrating on top brands, leaving the market for niche brands to be smaller. Especially those niche mobile phones that have grown up in market segments. When the leading brands make up for their shortcomings, maximize their performance, and turn around to invade their hinterland, they have almost no ability to resist.
This is the decline of Asus, Black Shark, and Savior. The original market for gaming phones has basically been eaten up by major manufacturers.
Of course, originally niche mobile phone brands were expected to survive by relying on sentiment and some loyal fans, and slowly looking for new opportunities, but this hope was completely crushed by the upstream supply chain.
Since last year, the supply of memory chips has been tight and prices have skyrocketed. Large manufacturers can use tens of millions of shipments to amortize costs, while niche manufacturers have no bargaining power in the supply chain. They cannot get preferential prices, or even the goods. An employee of a leading smart hardware company said, "There is news in the industry that small manufacturers can't get memory at all now, and large manufacturers can only buy it at a higher price, and the prices of downstream products will also increase."
Moreover, niche mobile phone brands are mostly concentrated in the mid-to-low-end market, and their profits are already thin. Memory costs have soared, and the mobile phone business does not make money, making it a loss-making business.
IDC estimates that the storage cost ratio of low-end models has increased from 10% to 15% in the past to 40% to 50%; Omdia estimates are even higher, with this ratio exceeding 64% for models under $99. The further downstream you go, the weaker your transferability is. Niche mobile phone manufacturers such as Meizu and Asus are even more unable to absorb costs through scale.
Not only niche mobile phone brands, but also large-scale leading manufacturers have been forced into danger. The most typical example is Transsion. In order to stock up on cores, Transsion "died into the family's assets" and borrowed money at the same time, which put huge pressure on the company's capital chain. The financial report shows that the net cash outflow from operating activities in the first three quarters of this year expanded from less than 5.9 billion yuan in the first half of the year to nearly 9.9 billion yuan, compared with a net inflow of 3.285 billion yuan in the same period last year.
Hoarding cores cannot really reduce costs, but can slow down the rate of cost increases. The essence is to exchange cash and inventory risks for a period of cost time difference. If it cannot complete the price increase and product structure adjustment within the time window obtained by "hoarding cores", Transsion is likely to be crushed.
Keeping the main business is the best way
The storm of memory chips has swept not only the mobile phone industry, but also the computer market. Nearly 40% of the cost of a PC is consumed by memory and hard disk. The price of the whole machine is pushed up, and the demand for replacement is greatly suppressed. It can be seen that the squeeze of memory on the PC market has evolved from a cost issue to a structural contradiction.
Asus' position in the PC market has always been awkward. On the ranking list, the top three have long been occupied by Lenovo, HP, and Dell. Apple is unique with its closed ecosystem, and Asus relies on gaming notebooks to support the market. As the well-known overlord of the motherboard market, affected by the AI wave, the PC motherboard market is experiencing systematic shrinkage, and ASUS's business has inevitably declined.
According to the latest report from DIGITIMES, the shipments of the world's four major consumer PC motherboard manufacturers, ASUS, Gigabyte, MSI, and ASRock, are expected to shrink by 28% overall in 2026, with a total reduction of approximately 11.7 million units. Among them, ASUS will ship 15 million motherboards in 2025, but will struggle to ship only more than 5 million in the first half of 2026. It is expected to barely hold on to the 10 million mark for the whole year, a year-on-year plunge of 33%. The only good thing is that the AI server business is growing rapidly and has become a new driving force for improving performance.
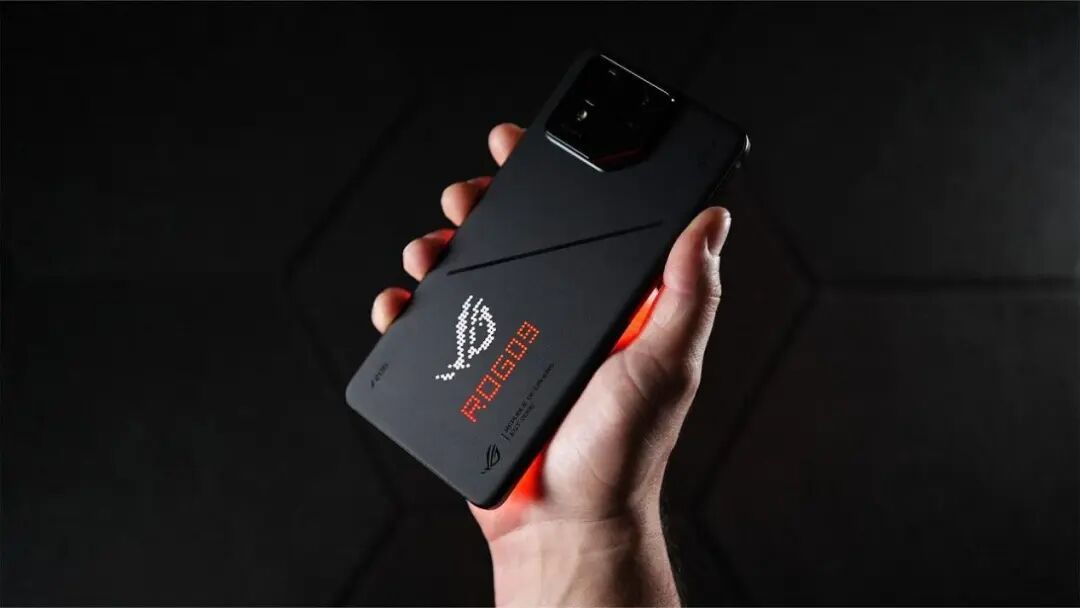
In this context, for Asus, the mobile phone business is even more burdensome. Compared with the main business, mobile phone revenue has long accounted for less than 10%, and it has suffered losses all year round, and has never been able to achieve stable profitability. In 2018, Chairman Shi Chongtang admitted that the mobile phone business failed. The financial report that year suffered a one-time loss of approximately NT$6.2 billion (approximately RMB 1.36 billion) due to the restructuring of the business.
Abandoning an unprofitable mobile phone business and focusing on its main business has become the most realistic choice for ASUS.
Looking back at the development history of my country's mobile phone industry, niche mobile phones can be said to be "products" left over from the fierce market competition. Those that can survive for many years mainly rely on or are backed by hardware giants or Internet giants. However, when giants or large manufacturers generally enter the era of "pure living", maintaining the core business is far more important than continuing to "stand" on the mobile side through the mobile phone business, especially now that there is almost no room for niche mobile phones to survive.
Lenovo and Asus are in a very similar situation. Although Lenovo's AI mobile phone has achieved growth, it is classified into the Others camp in the global smartphone statistical list. The mass consumer market has a weak voice, and only some overseas markets retain a certain volume. Moreover, the AIoT product line is widely spread, but so far there is no national-level hot product.
The explosion of computing power business cannot conceal the reality of uneven development of C-end consumer hardware.
Leave it or keep it? As the memory storm sweeps the entire mobile phone industry, this problem has obviously become more urgent. At present, Asus and Meizu (Geely) have made their choices, Lenovo may be waiting and watching, and ZTE has already started to take action. Just a few days ago, news came out that ZTE is negotiating with a major Internet manufacturer in mobile phone business cooperation, and the plan involves packaging ZTE’s mobile phone business.
Growth, highlights, turning points, and decline. Although all niche mobile phones have almost come to an end, they have also left a mark in the development history of domestic mobile phones.
Leaving a decent turn may be the best ending.
Comments